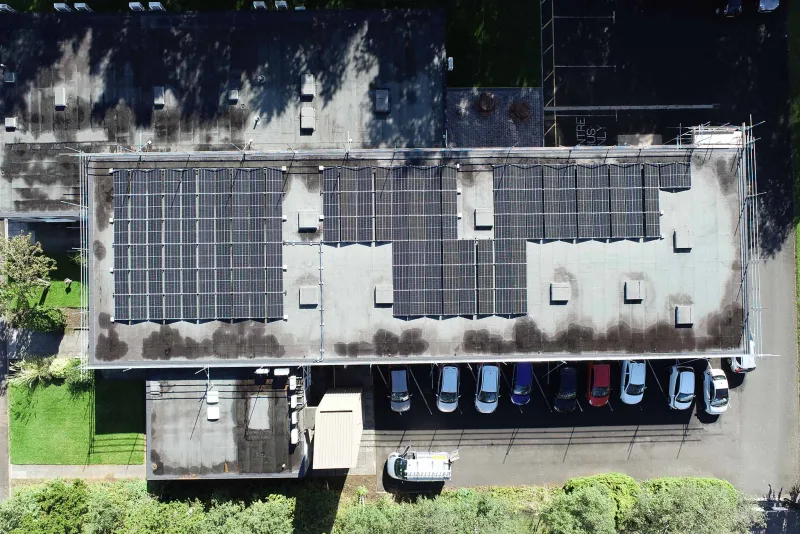
Buying the system outright is the route we recommend wherever the capital is available: you own a quarter-century asset from day one and keep the full return inside your business.
Capex means buying the solar system outright, as a capital asset your business owns. It is the simplest of the funding routes and the one we recommend wherever the capital is available, because nothing sits between you and the return. There is no funder taking a margin, no monthly charge and no power tariff to buy back. You own the panels on the roof and you keep every pound the system saves you for its working life.
The other routes on this hub exist for businesses that need the cash flow instead of the capital outlay. Each trades a share of that return for an easier balance-sheet entry. We frame every one of them against capex for exactly that reason: where you can fund it outright, outright keeps the most in the business.
01
The mechanics, plainly.
You pay for the system up front and the asset goes on your balance sheet. A well-designed commercial array is a long-life asset, typically rated for around 25 years, so you carry it and you keep the saving it produces for that whole period. Because you own it from day one, the generation it offsets against your import bill is yours in full, and the surplus you export is yours to monetise through an export route. The value sits in self-consumption: an exported unit pays far less than a unit you avoid buying, so we design for using the power on site first.
Capex also gives you the tax relief in the year you buy. Solar PV is a special-rate asset, and the Annual Investment Allowance gives a 100% first-year deduction within the £1m annual AIA limit, which brings the relief forward rather than writing the cost down over many years. Full expensing does not apply to solar, and the former super-deduction did not either, so the Annual Investment Allowance is the route to the first-year deduction. That is the honest hook, not tax advice. The exact relief depends on your profits, your other capital spend against the £1m limit and your accounting period, so confirm the position with a qualified accountant or tax adviser before you rely on it.
02
The capital buys a working asset, and it keeps paying long after it has paid for itself.
What you are buying is generating plant with a long design life, not a subscription. Commercial modules are typically warranted on a performance curve running to around 25 years, and a well-built array carries on producing beyond it at a reduced output. That matters to the capex case in a way it does not to any other route, because once the system has covered its own cost every further year of generation is margin. A funder's agreement, by contrast, tends to run for a fixed term and take the good years with it.
Owning the asset also means owning its upkeep, and we would rather put that on the table than leave it as a surprise. Inverters are the shortest-lived part of a commercial system and should be planned for as a mid-life replacement rather than treated as a fault when it happens. Monitoring, periodic inspection, cleaning where the site needs it and the electrical retest interval all sit with you. None of that is large against what the array generates, but it belongs in the model, so we set the operations and maintenance position out alongside the generation figures rather than after the order.
The other half of ownership is control. You decide when to add battery storage, when to extend the array onto a second roof, who maintains it and what happens at end of life. Under a lease the asset is yours but the finance agreement is not, and under a power purchase agreement neither is. If the building or the business changes, the route that leaves you holding the asset is the one that leaves you with options.
Funding routes, side by side
Three ways to fund the system
RecommendedBuy outright
Capex
Buy the system outright as a capital asset your business owns. Nothing sits between you and the return, so where the capital is available this keeps the most in the business.
Own a long-life asset from day one
Keep every pound of saving for its working life
Claim the first-year capital-allowances relief on the spend
The trade-off: it ties up capital and the asset sits on your balance sheet
Spread the cost
Leasing / hire purchase
Pay for the system over time rather than all at once, so the saving on the bill helps carry the cost of the finance. The system can be close to cash-flow neutral from the start.
Protect working capital while the system generates from day one
Under hire purchase you own the asset at the end of the agreement
A finance charge sits in between that capex does not carry
On-or-off balance sheet under IFRS 16 or FRS 102 depends on the contract
No capital outlay
PPA / roof rental
A third-party funder pays for and owns the array, and you buy the power it generates at a contracted rate, usually below the grid price. You get cheaper on-site electricity with nothing on the bank balance.
Zero capital outlay, with the import saving usually starting in year one
A long agreement, often well over a decade
The funder owns the asset and claims the capital allowances
A PPA largely benefits the funder, who keeps most of the long-term return
03
A capex case goes to the board on evidence, so here is what we put in it.
A capital request for generating plant is judged like any other capital request, which means the paper has to stand on its own. We build it from four things. Your half-hourly consumption data for a full year, because the value of the system is set by how much of its output you use on site rather than by how much it generates. An on-site drone survey flown by our own qualified, insured pilot, which gives real roof geometry, real shading and real obstructions instead of a satellite trace. A PV*SOL model built on that survey, which is the bankable-grade software lenders model against. And the connection position with your distribution network operator, because a G99 application is what usually paces a commercial programme.
From those we produce the split between self-consumed and exported generation, the resulting import saving, the year-one capital-allowances position on the spend, and the maintenance cost over the life of the asset. We model the conservative end rather than the best case, because a board paper that overstates the return is the one that gets found out in year two. Where a figure is sensitive to something outside our control, such as your import tariff at renewal, we show it as a range with the assumption named rather than as a single number.
We do not publish a per-kWp figure or a headline payback on this page, and we will not put one in an email before the survey. One costed figure for your building, produced after the roof has been looked at, is worth more to a finance director than a rate that has to be revised. The first feasibility read costs you nothing.
04
Capex is the wrong call in a few specific situations, and we will tell you when yours is one of them.
The relief that makes capex strongest only has value against tax you actually pay. If the business has little or no taxable profit in the year of the spend, or has already used its Annual Investment Allowance headroom on other capital, the first-year deduction does less work and the case rests on the energy saving alone. It may still be a good case. It is simply a different one, and your accountant should size it before the board sees it.
Tenure is the second test. If you occupy the building on a lease with only a few years left, or on terms that do not let you fix generating plant to the roof or take it with you, buying an asset with a 25-year life is the wrong shape for the commitment. The same applies where the roof covering is near the end of its own service life, because the honest sequence is to replace the roof first and mount the array on it afterwards rather than pay twice to remove and refit a system.
The third test is the cost of the capital itself. Where the money would otherwise earn or save more elsewhere in the business, or where borrowing to buy costs more than the system returns, spreading the cost or letting a funder carry it is the rational answer. That is what the alternatives to buying outright are for, and we will set them beside capex on your own modelled figures rather than steer you to the route that suits us. None of this is financial or tax advice; confirm your own position with a qualified adviser before you commit.
05
Who it suits, and the trade-offs.
The trade-off with capex is plain: it ties up capital. You commit the full cost up front and the asset sits on your balance sheet rather than off it. For a business with the cash, or one that would otherwise leave it earning little, that is the point, because you keep the saving and the tax relief rather than handing a slice to a funder. For a business that needs to protect working capital, leasing or hire purchase spreads the cost so the system can be cash-flow neutral, and a power purchase agreement removes the outlay entirely, though a PPA largely benefits the funder who owns the asset.
Capex is the better call wherever the capital is available and the cost of that capital is lower than the return the system earns. Grants can in principle reduce the outlay, but they exist mainly for eligible public-sector bodies and specific schemes; most private commercial sites do not qualify, so we will tell you straight whether yours does rather than build a case around money that is not there. Whichever way you fund it, your own figures come from the on-site survey and the PV*SOL model, not from a rule of thumb.
Indicative, not financial or tax advice. Confirm the position with a qualified accountant or tax adviser. Your figure comes from a survey-led PV*SOL model.
FAQ
Capex (buy outright) for commercial solar: common questions
Because it keeps the most of the return inside your business. With capex you own a roughly 25-year asset from day one, you keep every pound of saving, and you claim the first-year capital-allowances relief. Leasing, hire purchase and a power purchase agreement all trade some of that return for easier cash flow, which is the right call for some businesses but not the best return where the capital is available.
Solar PV is a special-rate asset, and the Annual Investment Allowance gives a 100% first-year deduction within the £1m annual AIA limit. Full expensing does not apply to solar, and the former super-deduction did not either, so the Annual Investment Allowance is the route to that first-year deduction. This is indicative, not tax advice; the relief depends on your profits and your other capital spend, so confirm the position with your accountant or tax adviser.
Yes. With capex you own the asset, so it sits on your balance sheet, which is the straightforward treatment. That is one of the differences from leasing or a PPA, where whether the arrangement sits on or off balance sheet depends on the contract terms under IFRS 16 or FRS 102 and is a question for your auditor.
You can, through an export route such as the Smart Export Guarantee, a PPA or a wholesale arrangement, and as the owner that income is yours. The value is far smaller than the value of the power you use on site, because an exported unit pays much less than a unit you avoid buying. That is why we design a bought system for self-consumption first and treat export as a way to monetise the surplus, not the main return.
Get a commercial quote
Get the numbers for your roof, not a from-price.
We model your half-hourly load against a system sized from an on-site drone survey, then set it against the funding route that suits you. Capex first, because it keeps the most of the return, with leasing and a PPA there if the cash flow needs them.
Capex-first, with leasing, hire purchase and a PPA if you need them
Indicative figures from a survey-led PV*SOL model, with no from-price
Not financial or tax advice; we point you to a qualified adviser